
Ghana
Category
7 of 7
| Risk type | Short | Long |
|---|---|---|
| Sovereign |
 Normally off cover |
Normally off cover
|
| Public |
Normally off cover
|
Normally off cover
|
| Bank |
 Normal risk assessment |
Normal risk assessment
|
| Corporate |
Normal risk assessment
|
Normal risk assessment
|
The icons indicate EKN's risk assessment.
A lower country risk category means a lower country risk. The icons mark EKN's ability to cover risks to different buyers in the country.
-
 No policy established
- EKN has not analysed this country recently and therefore has no current opinion. If an exporter submits an application for such a country, EKN performs an analysis of the country at short notice and determines a policy.
-
Normal risk assessment
- EKN decides on guarantee issue based on an assessment of risk in the transaction. There are no predefined restrictions in the risk assessment or assumptions for risk assessment.
-
 Restrictive risk assessment
- EKN sets stricter requirements in the risk assessment in order to guarantee a transaction. EKN may have specified special criteria that are key to the risk assessment of the guarantee holder category in question. This may mean that EKN sets a requirement that the counter party must have its own hard currency earnings or that external support can be expected, or that EKN sets a requirement for a letter of credit, government or bank guarantee. If the formulation of the transaction deviates from a defined restriction, we normally set more stringent conditions and may in the worst case refuse to guarantee the transaction. More stringent conditions may be that we reduce the sum guaranteed, raise the premium or require some form of security.
-
Normally off cover
- Here EKN does not normally cover currency transfer risks. However in some circumstances EKN may be able to go further with high risk countries than the restrictions of the country policy indicate. The application is then tested under the so-called GSL facility, which refers to guarantee issue with special country evaluation. There are specific requirements for this, primarily that the exporter has experience of the market in question. The risk is then shared with the exporter and by means of a mark-up on the premium.
-
 OECD or EU countries
- Because of EU rules, EKN cannot issue guarantees for transactions with a risk period of less than two years for exports to Australia, EU countries, Iceland, Japan, Canada, Norway, New Zealand, Switzerland or the USA. If you have any questions, please telephone us on +46 8-788 00 00.
Country risk analysis
Country Risk Analysis of Ghana
The latest Country Risk Analysis of Ghana was issued in October 2026.
Background
Over the past decade, Ghana has recorded average GDP growth of approximately five per cent per year. Agriculture plays an important role in employment, while exports are dominated by gold, oil and cocoa. Thanks to high gold prices, gold alone accounts for over 50 per cent of export revenues. Ghana is generally one of the more dynamic economies on the continent. Unlike many other African countries, GDP per capita growth is close to three per cent. This, combined with relatively strong institutions, constitutes the country’s main strengths.
Although the country’s institutions and freedom of expression have gradually weakened over the past decade, the risk of Ghana being drawn into the wave of anti-democratic developments sweeping across West Africa is nevertheless assessed as low. Peaceful transfers of power have taken place regularly since 1992, and violence in connection with these transitions is rare.
Ghana’s weaknesses include its public finances. Low revenues combined with excessive spending have led to recurring budget deficits, unsustainable debt financing and IMF programmes. The historically weak fiscal discipline means that the current IMF programme is the eighteenth since independence in 1957. Both the governing NPP party and the opposition NDC party have mismanaged public finances during their respective periods in government.
Ghana received substantial debt relief in the early 2000s under the Heavily Indebted Poor Countries (HIPC) Initiative. Due to the continued deterioration in public finances, EKN downgraded Ghana to country risk class 7 in June 2022 and closed for sovereign risk exposure in September of the same year.
The oil and gas industry is important for maintaining high economic growth, which entails some transition risk, particularly as Ghana is a high-cost producer of oil and gas. Low income levels and a large agricultural sector also make the country vulnerable to climate-related risks, particularly flooding and storms. The country’s cities and industrial production are largely concentrated in coastal areas. The important cocoa industry is sensitive to drought. In the 2024 ND-GAIN Index, which measures countries’ vulnerability to climate change and their capacity to manage related risks, Ghana ranks 108th out of 190 countries.
Back on track
Like the rest of the world, Ghana’s economy is affected by the war in the Middle East. Higher oil prices and tighter financing conditions are negative for an import-dependent and heavily indebted economy such as Ghana’s. Since the closure of the Strait of Hormuz, pressure on the cedi has increased and foreign currency liquidity has tightened. Gold exports have also experienced disruptions, although high prices have provided some compensation.
The most evident consequence, however, has been rising food prices in recent months. Food accounts for a disproportionately large share of the consumer price index in African economies, and in Ghana this share is 40 per cent. In addition, food imports account for just over 15 per cent of total imports, creating inflationary pressures when import and transport costs rise.
Fertiliser prices have also increased in the wake of the war in the Middle East. Combined with transport disruptions and a delayed planting season, this risks creating a lagged inflationary impulse in 2027. This could, in turn, coincide with and be amplified by the unusually strong El Niño event that is highly likely to affect Ghana during autumn and winter 2026/2027. Agricultural harvests, including those in the important cocoa industry, could suffer crop failures due to heavy rainfall and plant diseases. During the last strong El Niño event in 2015/16, inflation rose by several percentage points.
However, Ghana’s economy has developed positively over the past year and exhibits resilience. The war in the Middle East has therefore not resulted in a hard landing so far. Although growth has not returned to pre-COVID-19 levels, it remains relatively strong at around five per cent. Almost all of the Bank of Ghana’s (BoG) leading indicators, including container traffic and vehicle registrations, continue to point upwards.
Inflation has declined from 54 per cent in 2022 to 5.0 per cent, according to the latest figure from BoG. This has enabled five interest rate cuts since May 2025*. Thanks to the IMF programme, deferred external debt payments and high export revenues from gold, the current account surplus is substantial, equivalent to eight per cent of GDP. Over the past six months, Ghana’s domestic oil production has also had a stabilising effect. Direct trade with the Gulf states is limited across all goods categories, and Ghana has the option of importing oil from regional exporters.
Foreign exchange reserves declined by USD 1 billion to USD 13 billion during the second quarter of 2026 due to the war in the Middle East. However, reserves are eight times larger than in 2022 and correspond to just over four months of import cover. According to the IMF’s forecast, reserves will increase to six months of import cover by 2029, which the IMF considers an adequate level for Ghana’s economy.
The cedi has stabilised at around 11 cedi per USD, and overall foreign currency liquidity in the economy has improved compared with the crisis years of 2022–2024. One reason is gold production and purchases under the Domestic Gold Purchase Programme (DGPP)**. Another reason is that BoG introduced a system of foreign currency auctions in 2025. These reforms have improved transparency and increased supply.
However, the foreign exchange market is still not functioning optimally, and demand for foreign currency exceeds supply. Government interventions are common, which according to the IMF results in multiple exchange rates. For example, to support the cedi and balance demand, BoG sold just over USD 8 billion on the foreign exchange market during the first seven months of 2026.
Public finances continue to move in the right direction. The IMF programme was concluded during summer 2026, having been implemented largely satisfactorily. The restructuring of domestic public debt has been completed, while the restructuring of external public debt is virtually complete. As a result, public debt has declined to just over 50 per cent of GDP and the budget deficit amounts to just over two per cent of GDP, both moderate levels.
Several important fiscal reforms have been implemented to address the debt problems. For example, a tax reform has been carried out under which several special levies, including one introduced during COVID-19, have been incorporated into VAT. The Public Finance Management Act has been updated with a debt anchor of 45 per cent of GDP by 2034 and a primary budget surplus target of 1.5 per cent of GDP***.
Thanks to fiscal consolidation and reforms, the IMF now assesses the risk of public debt distress as moderate, compared with the previous assessment of high risk. Ghana has applied for a 36-month unfunded programme, the Policy Coordination Instrument (PCI), which should support continued fiscal discipline over the coming years.
Over the longer term, implementation of the reforms mentioned above and continued fiscal discipline will be crucial for the sustainability of public finances. Debt consolidation has been driven almost exclusively by expenditure reductions, which represents a weakness. Ghana’s main problem lies on the revenue side, where revenues as a share of GDP are among the lowest in the region. Public debt interest costs correspond to just over one-fifth of government revenues. According to the IMF’s forecast, revenues will increase moderately over the coming years to 17 per cent of GDP, which remains low.
Despite substantial social and infrastructure needs, government expenditure must remain prudent in the coming years. According to the IMF, Ghana has limited scope for external borrowing over the next few years, at approximately USD 1.2–1.3 billion per year in present value terms. Although the situation has improved, both the banking sector and state-owned enterprises continue to pose fiscal risks for Ghana that need to be managed.
In addition, the now substantial dominance of the gold sector represents a risk if gold prices were to decline. A significant part of the recovery in the economy and public finances is attributable to favourable developments in international gold prices.
It is not until 2027, when Ghana is due to resume payments on external loans, that EKN will obtain an indication of the government’s external repayment capacity. EKN therefore maintains Ghana’s country risk classification at class 7 of 7 and remains closed for sovereign risks. For EKN to reopen for sovereign risks, a bilateral agreement must be in place and Ghana must demonstrate repayment capacity during 2027.
Business environment
High growth, political stability, a relatively open economy and reasonably well-functioning institutions provide the foundations for a favourable business environment. In the World Bank’s Worldwide Governance Indicators, the country’s economic institutions score 52 out of 100 on average across the Rule of Law, Regulatory Quality and Control of Corruption indices, slightly above the midpoint. One contributing factor is the country’s relatively free and independent media, which scrutinise those in power.
EKN’s experience indicates that, for example, repossession of equipment through the legal system functions satisfactorily, although there are clear shortcomings in the country’s bureaucracy and judicial system. Foreign currency liquidity has generally improved. Regarding public buyers, EKN’s experience continues to indicate that the risk of delayed payments from public sector debtors is higher than normal. Payment delays and claims have arisen due to late payments from the state institution Cocobod, and further delays have occurred during 2026 due to non-payment by another public sector debtor.
In its business assessments, EKN considers the risk of adverse impacts on human rights. The focus is on potential impacts arising from the operations in which exported goods are used. Key issues include working conditions, child and forced labour, excessive use of force by security forces, indigenous rights and land rights.
According to Verisk Maplecroft’s human rights index, Ghana exhibits a significantly higher risk profile across all these indicators compared with OECD high-income countries. See chart . See chart. The differences are particularly pronounced regarding the risks of forced labour, child labour, and occupational health and safety. Compared with countries at a similar income level, Ghana also has a somewhat higher risk level regarding forced labour and child labour.
EKN’s policy
EKN classifies Ghana in country risk class 7 of 7. Since September 2022, EKN has been closed for direct sovereign risks. Such transactions require a letter of credit or bank guarantee. Normal risk assessment applies to bank and corporate risks.
EKN’s commitment and experience
Sovereign risks amounting to SEK 2.3 billion after reinsurance, account for the majority of EKN’s exposure. All of these will be included in the Paris Club agreement between Sweden and Ghana. This entails claims payments of just over SEK 1 billion during 2023–2026, with repayments scheduled for 2039–2043. So far, claims amounting to just over SEK 800 million have been settled. These transactions also account for the majority of payment delays. EKN also has an outstanding claim of SEK 14 million against another public sector counterparty that is not covered by the debt agreement.
In the private sector, EKN issues guarantees for 20–30 transactions per year, mainly in the mining and transport sectors. Payment experience deteriorated during the economic crisis, particularly among buyers in the paper industry. However, payment delays and claims involving these buyers have declined over the past year. By contrast, delays and claims have increased in the transport sector, where the underlying cause is non-payment under government contracts.
* The policy rate has been reduced by a cumulative 1,400 basis points, resulting in a decline in banks’ average lending rates from 27 per cent to 15 per cent.
** The DGPP has had an effect, but has also been costly for the Bank of Ghana due to substantial exchange rate losses. As a result, BoG will require a capital injection. During 2026, the DGPP was transferred to a new state institution, GoldBod, and will therefore no longer burden BoG’s balance sheet.
*** In addition, the Ghana Integrated Financial Management Information System (GIFMIS) has been expanded and a Treasury Single Account introduced to increase transparency in public expenditure. A Value for Money office will be established from 2027.
Learn more about exporting to Ghana
- Sustainability
- Financing
“Water is life”
A major project in Ghana will deliver clean drinking water to 400,000 people, transforming lives and supporting development.
“Water is life”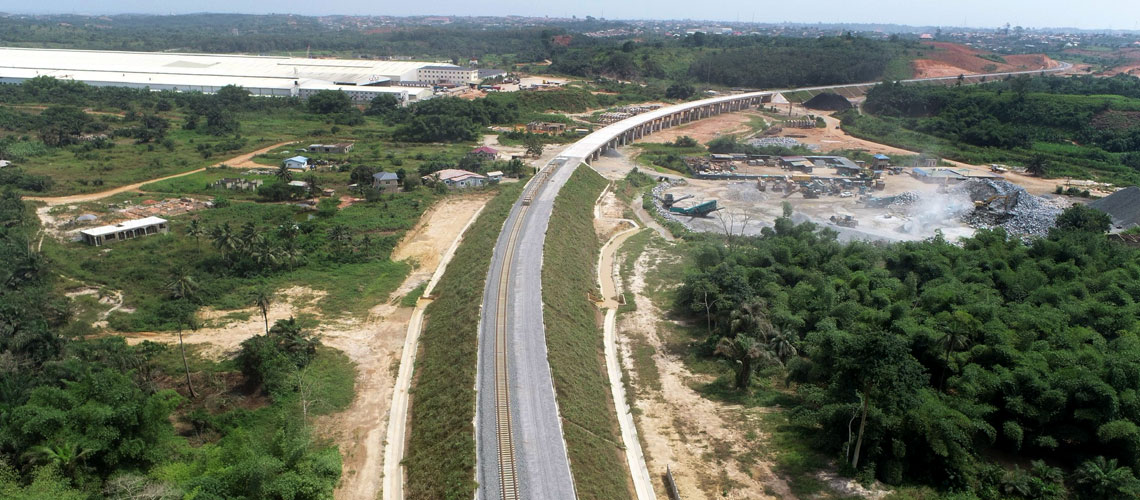
- Sustainability
- Financing
Fast track to growth in Ghana
In Ghana, EKN-backed financing enables the biggest railway investment since independence. The project will boost exports, create new jobs and add to sustainability by shifting cargo from road to rail.
Fast track to growth in Ghana
- Sustainability
- Bank
- Financing
Paving the way for progress
Cocoa, gold and oil, coupled with political stability, has placed Ghana in the top tier of African economies, but the quality of the infrastructure hasn’t quite kept up. That’s about to change.
Paving the way for progressMore for companies that want to export to Ghana
EKN's guarantees
EKN's guarantees reduce the risk of payment defaults and help banks support businesses. Which guarantee suits your needs?
EKN's guarantees
Guarantee guide
Are you unsure which guarantee is the best fit for your specific transaction? Try our guarantee guide.
Guarantee guide